Long-term financial planning sounds like something for people with trust funds and a guy in a suit. It isn’t. If you work for a living, you need a plan even more because you don’t have extra money to waste on bad credit, taxes you didn’t prepare for, or goals you never wrote down. The good news is that the core of planning is boring. Pick a target, automate the money, protect your credit, and check in before problems snowball. You can do this in a few hours a year, not every weekend.
Start with one goal and one date. Not five goals. Not a vague wish to be rich. Choose the thing that will hurt most if you ignore it: a six-month emergency fund, a down payment, retirement, or killing high-interest debt. Give it a number and a deadline. If you want $6,000 in savings in 18 months, that’s about $333 a month, $77 a week, or $11 a day. If that’s impossible, extend the deadline or cut one recurring expense. The exact math matters less than having a target. Once you have it, every spending decision gets easier because you know what you’re protecting.
Automate before you see the money. On payday, set a transfer to savings. Use a separate account so you’re not tempted to swipe it. For retirement, take the full employer match if your job offers one. That’s part of your pay. Then increase your contribution by one percent every time you get a raise. If you have a Roth IRA and qualify, use it. If you have a high-deductible health plan, an HSA can be a quiet retirement account with tax breaks on the way in, growth, and qualified medical withdrawals. You do not need to pick perfect investments. A low-cost target-date fund or broad index fund is enough. Boring is beautiful.
Your credit score is a long-term planning tool. It affects car loans, mortgages, insurance, and sometimes job applications. Payment history and credit utilization are the big two. Set autopay for at least the minimum on every card, then pay more when you can. Keep balances low relative to limits. Don’t close your oldest no-fee card just because you don’t use it. Check your official free credit reports and dispute errors. Avoid junk credit moves: store cards for a one-time discount, buy-now-pay-later plans you can’t cover, and cosigning for someone who won’t pay. A few points can cost you thousands over the life of a loan. That’s money you could be investing.
Taxes and estate basics belong in the plan too, even if you don’t own a house. Fill out your W-4 so you’re not giving the government an interest-free loan all year. If you get a huge refund, adjust your withholding and use the extra cash flow. If you have a side hustle, set aside 25 to 30 percent of profit for taxes. Keep receipts. Name beneficiaries on your 401(k), IRA, and life insurance. If you have kids or any assets, make a simple will. Beneficiary forms often override a will, so keep them current after marriage, divorce, births, or deaths.
Insurance is not a scam when it protects the plan. Health coverage, auto, renters, and disability insurance if work offers it are foundations. An emergency fund is also insurance. It keeps a dead car or a medical bill from becoming credit card debt. If you carry high-interest debt, usually above 10 percent, pay it off before investing beyond your employer match. Use the avalanche method and target the highest rate first. If you need motivation, pay the smallest balance first. Either way, automate the payment.
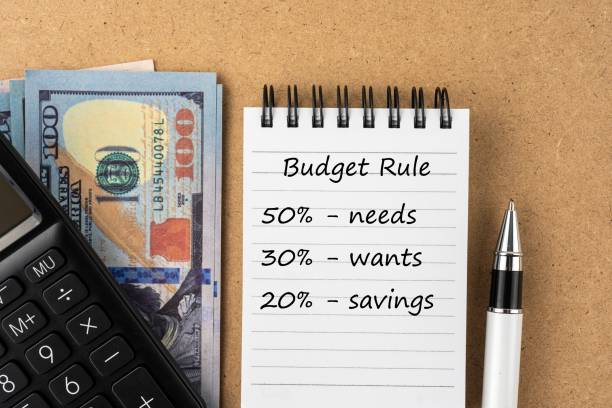
Review the plan once a quarter, not every day. Put 30 minutes on your calendar. Check your balances, your credit score, and your beneficiaries. Adjust one thing. When you get a raise, bonus, or tax refund, decide where it goes before it disappears. A simple split works: most to your goal, some to fun, some to buffer. Lifestyle creep is the silent goal killer.
You don’t need a pricey financial manager to build a solid future. You need consistent transfers, clean credit, tax basics, and a few legal documents. Do the boring stuff now so your future self isn’t stuck fixing today’s junk credit. The long game is won by people who show up automatically.